A manufacturer ships a component that does not meet specification. The customer discovers the problem before anyone is injured and before the component damages other property.
That sounds like good news—until the customer demands payment for rework, scrapped inventory, delayed production, expedited replacement parts and lost contracts.
The loss may be substantial, but the traditional product-liability policy may not have encountered the type of bodily injury or property damage required to trigger coverage. That is the space manufacturers errors and omissions coverage is designed to examine.
The Two Coverages Begin With Different Triggers
Product liability, commonly included within commercial general liability coverage, is generally concerned with claims alleging that a product caused bodily injury or physical damage to someone else’s property.
Manufacturers E&O focuses on certain claims alleging financial loss caused by an error, omission, negligent act or failure of the manufacturer’s product or work to perform as intended. No bodily injury or physical property damage may be required, depending on the policy.
The distinction matters because the same defective component can create several kinds of loss—and each part may be treated differently.
Where Product Liability May Respond
Consider a valve that fails after installation and releases fluid that damages the customer’s machinery. The damaged machinery may support an allegation of physical property damage caused by the manufacturer’s product.
The analysis would still depend on the allegations, policy language, exclusions, completed-operations terms and which property was damaged. Coverage for the manufacturer’s own defective product is often different from coverage for resulting damage to other property.
“A defective product and the damage caused by that product are not always treated as the same loss.”
Where the Financial-Loss Gap Appears
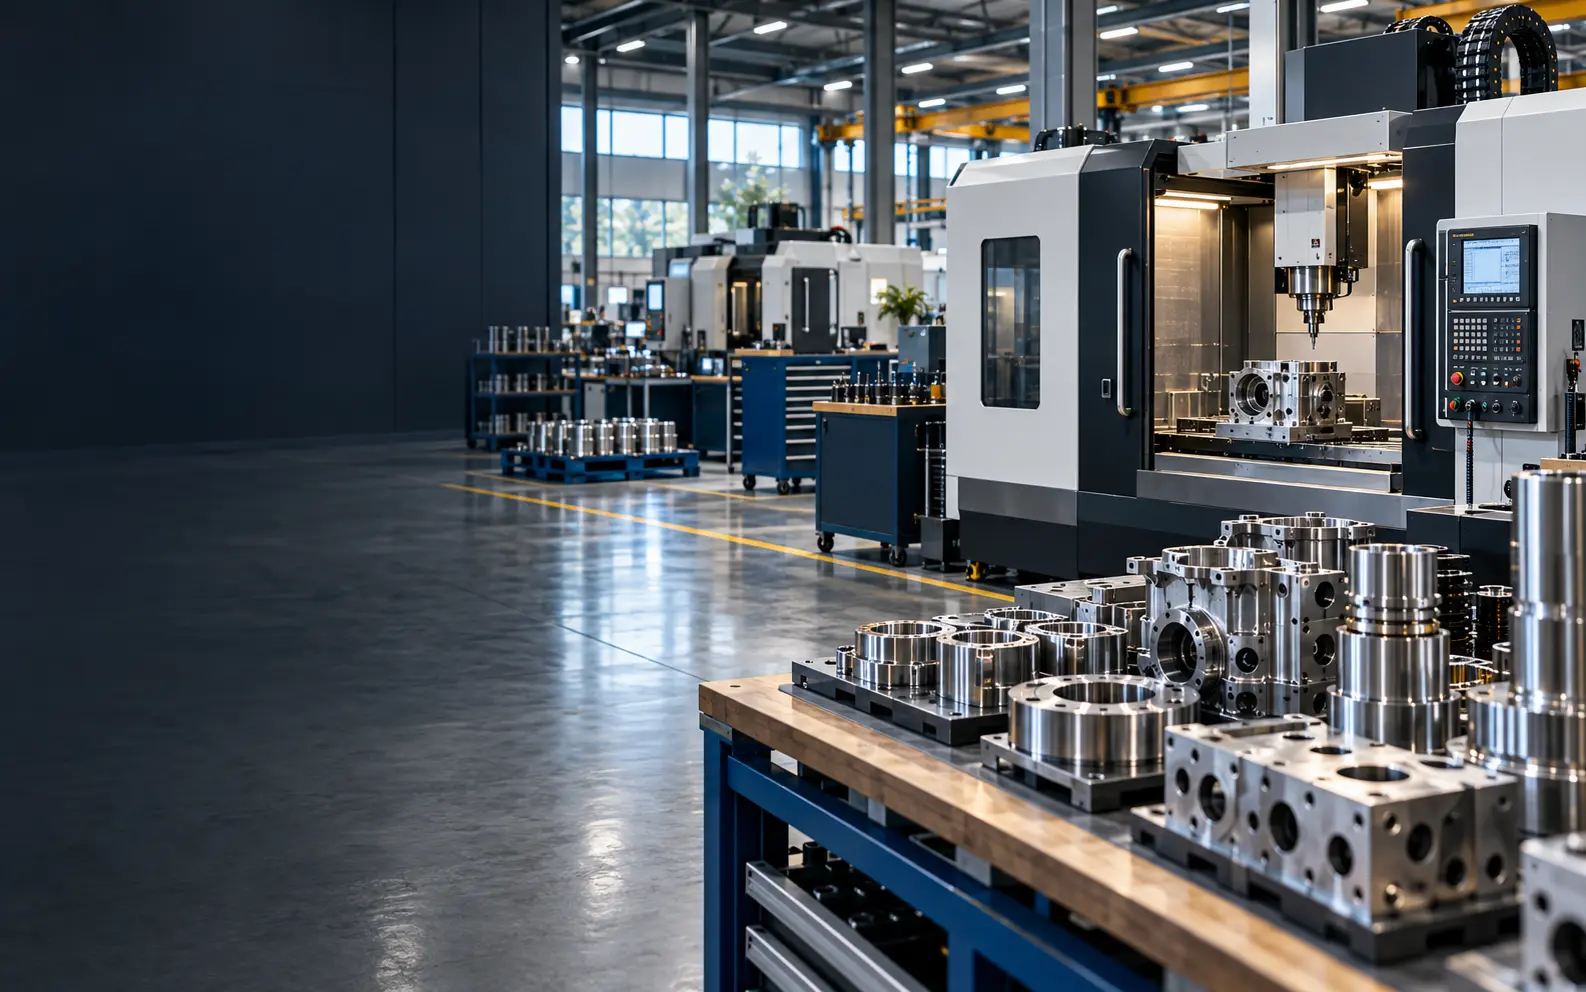
Now consider a precision component rejected before installation because it is outside tolerance. The customer shuts down its line, sorts inventory and sources replacements. Nothing else has been physically damaged.
The customer may still seek:
- Inspection costs
- Rework expense
- Scrapped inventory
- Replacement parts
- Expedited freight
- Production downtime
- Lost profits
- Contract penalties
Those are financial consequences of alleged faulty work or product performance. A general liability policy was not designed to cover every contractual or economic loss arising from an unsatisfactory product.
What Manufacturers E&O Is Intended to Address
Manufacturers E&O can provide protection for certain customer claims alleging that a product, component or service failed to meet specifications, perform as represented or satisfy contractual requirements.
Coverage varies considerably. Policies may define covered services, products, damages and wrongful acts differently. They may also contain exclusions involving warranties, guarantees, intentional acts, intellectual property, known circumstances, delays, recalls or the cost to repair or replace the insured’s own work.
The policy should be evaluated against what the manufacturer actually promises—not merely the description of operations on the application.
Connect product liability, recall and E&O
Review how the program responds when a product causes physical damage, fails financially or must be withdrawn from the market.
Product Recall Is a Separate Question
Neither general liability nor manufacturers E&O should be assumed to cover the full cost of finding, withdrawing, replacing or disposing of a defective product. Product-recall coverage is commonly structured separately and may address specified first-party and third-party recall expenses.
A single defect can therefore implicate several coverage areas: liability for resulting injury or damage, financial-loss allegations, the manufacturer’s own replacement costs and recall expenses.
The Contract Can Expand the Exposure
Customer agreements frequently contain warranties, specifications, indemnification provisions, service-level commitments, chargebacks, liquidated damages and broad definitions of recoverable loss.
A manufacturer may accept obligations that exceed customary legal liability or available insurance coverage. Limitation-of-liability language and exclusions of consequential damages can be as important to risk financing as the insurance policy itself.
Insurance and qualified legal review should happen before the contract is signed. A policy cannot reliably rescue every promise sales agreed to make on Friday afternoon.
Claims Rarely Stay in One Coverage Lane
A component failure may damage the customer’s equipment, contaminate finished goods, stop production and require a market withdrawal. The customer’s demand may combine all those costs in one letter.
The claim should be separated into its parts:
- What physically failed?
- Was anyone injured?
- Was property other than the insured’s product physically damaged?
- What costs relate to repair or replacement of the product itself?
- What costs arise from delay, downtime or lost profit?
- Was a recall initiated, and by whom?
- What did the contract require?
That analysis helps identify potentially applicable policies and prevents the entire demand from being treated as one convenient—but inaccurate—coverage category.
“The value of manufacturers E&O appears most clearly when the customer’s loss is real, significant and primarily financial.”
Build the Coverage Review Around Real Failure Scenarios
Manufacturers should identify how their products can fail, who depends on them and what the downstream consequences could be.
- Review customer specifications, warranties and performance guarantees.
- Map where products are installed and what operations depend on them.
- Estimate realistic rework, replacement, delay and recall costs.
- Confirm whether design, engineering or consulting services are provided.
- Coordinate general liability, manufacturers E&O and recall coverage.
- Maintain quality-control, traceability and change-management records.
- Establish a process for escalating complaints and potential claims.
When a Customer Makes a Demand
Preserve the product, specifications, drawings, quality records, communications and governing contract. Notify the insurance team promptly and avoid agreeing to reimburse costs or redo work before the demand and potential coverage have been evaluated.
Separate the customer’s claimed damages by category and timeline. Early clarity about the allegations can materially improve the coverage presentation and response strategy.
Coverage depends on the allegations, policy language, definitions, exclusions, endorsements, contracts and facts of the claim. Manufacturers E&O, product liability and product-recall policies vary. This article does not guarantee coverage or constitute legal advice.